সূচিপত্র
১. সংক্ষিপ্ত উত্তর
ভাড়া হতে আয় সব সময় মাসিক প্রাপ্ত নগদ অর্থ × ১২ নয়। প্রথমে আইন অনুযায়ী মোট ভাড়ামূল্য নির্ধারণ, সম্পত্তির ধরন অনুযায়ী অনুমোদনযোগ্য বিয়োজন এবং এরপর বিশেষ ভাড়া আয় যোগ করতে হয়। প্রযোজ্য tenant কর্তৃক কর্তিত tax আলাদাভাবে tax credit—এটি gross rent কমায় না।
| বিষয় | বর্তমান ব্যবহারিক অবস্থান |
|---|---|
| Residential House Property | নির্দিষ্ট collection, utility, service, repair ও maintenance expense-এর জন্য মোট ভাড়ামূল্যের ২৫% statutory deduction। |
| Commercial House Property | একই statutory expense group-এর জন্য মোট ভাড়ামূল্যের ৩০% deduction। |
| Other Property | ২৫%/৩০% shortcut নয়; ধারা ৩৮(২), ধারা ৪৯–৫৫ ও প্রযোজ্য bank-transfer condition অনুসরণ করতে হবে। |
| Refundable/adjustable deposit | বছর শেষে outstanding balance-এর ১০% বিশেষ ভাড়া আয়। |
| Rent TDS | শুধু section 109-এর specified-person tenant ও listed property-এর ক্ষেত্রে ১০%। |
২. ভাড়া হতে আয়: হিসাব, TDS ও e-Return প্রক্রিয়া
প্রতিটি property-এর জন্য এই ধারাবাহিকতা অনুসরণ করুন। এতে income computation ও source-tax credit আলাদা থাকে এবং lease, bank ও tenant record-এর সঙ্গে return সহজে reconcile করা যায়।
Asset classify করুন
House Property বা Other Property নির্বাচন এবং own-business অংশ আলাদা করুন।
Gross rental value হিসাব করুন
Annual value ও tenant-paid charge যোগ; electricity bill দিয়ে vacancy support করুন।
আইনসম্মত deduction দিন
House Property বা Other Property rule—দুটি একসঙ্গে নয়।
Special rental income যোগ করুন
Deposit, advance, salami, premium, unspent claim ও disallowed expense review করুন।
Section 109 TDS মিলান
Tenant status, gross rent, deduction, government deposit ও certificate যাচাই করুন।
e-Return-এ property যোগ করুন
সঠিক type ব্যবহার করে প্রয়োজন হলে প্রতিটি property আলাদা add করুন।
Credit claim ও evidence রাখুন
Eligible source tax আলাদা claim করে return ও acknowledgement সংরক্ষণ করুন।
৩. আইনগত কাঠামো ও সম্পত্তির শ্রেণিবিন্যাস
আয়কর আইন, ২০২৩-এর ধারা ৩৫–৩৯ ২০২৬–২৭ করবর্ষে ভাড়া হতে আয়ের classification ও computation নির্ধারণ করে। আইনগত exception এবং মালিকের own-business use ছাড়া, letting-এর commercial nature যাই হোক, ধারা ৩৬ সাধারণভাবে property rent-কে এই head-এর অধীনে রাখে।
House Property ও Other Property
| Category | সাধারণ asset | প্রধান tax consequence |
|---|---|---|
| House Property | Building/structure, integral furniture-fixture-fitting, appurtenant land এবং warehouse হিসেবে ব্যবহৃত structure | ধারা ৩৮(১), residential/commercial statutory percentage |
| Other Property | Land, machinery, non-integral furniture, plant-সহ factory building, business premises, vehicle ও অন্যান্য rentable tangible capital asset | ধারা ৩৮(২); ২৫%/৩০% statutory shortcut নয় |
Rental income নাকি Business Income?
Agreement-এর label চূড়ান্ত নয়। Hotel, motel, hostel, resort এবং নির্দিষ্ট economic-zone/high-tech-park developer arrangement আলাদা analysis চায়। মালিকের নিজস্ব business বা profession-এ ব্যবহৃত অংশের আয় সঠিকভাবে business/professional income হলে rent chapter-এর treatment প্রযোজ্য নয়।
৪. মোট ভাড়ামূল্য ও অনুমোদনযোগ্য বিয়োজন
বর্তমান ধারা ৩৭ অনুযায়ী মোট ভাড়ামূল্য = annual value + tenant-paid service/repair/maintenance charge − vacancy allowance। Vacancy allowance-এর জন্য electricity bill আবশ্যক। এরপর ধারা ৩৮ property category অনুযায়ী deduction দেয়।
House Property deduction
- গৃহসম্পত্তির ক্ষতি বা ধ্বংসের ঝুঁকির insurance premium।
- Acquisition, construction, renovation বা reconstruction-এর qualifying bank/finance-company capital loan interest/profit।
- Property-সংক্রান্ত non-capital tax, fee বা annual charge।
- Qualifying pre-rental loan interest—প্রথম rental income year থেকে তিন সমান কিস্তিতে।
- Collection, utility, service charge, repair ও maintenance-এর জন্য ২৫%/৩০% statutory deduction; partial ও part-year letting-এ proportionate limit।
Residential ও Commercial তুলনা
| House Property-এর ব্যবহার | Statutory deduction | ১২,০০,০০০ টাকা gross rental value-তে |
|---|---|---|
| Non-commercial/residential | ২৫% | ৩,০০,০০০ টাকা |
| Commercial | ৩০% | ৩,৬০,০০০ টাকা |
Other Property deduction
House Property ছাড়া অন্য property-তে ধারা ৩৮(২) অনুযায়ী ধারা ৪৯–৫৫-এর relevant business-deduction rule, limit ও condition প্রযোজ্য। Third Schedule allowance ছাড়া অন্যান্য deduction bank transfer-এ paid হতে হবে। Unsupported, personal, capital বা non-compliant expense disallow হয়ে special rental income তৈরি করতে পারে।
হিসাবের উদাহরণ
| Residential apartment example | Amount |
|---|---|
| Annual value | ১২,০০,০০০ টাকা |
| Tenant-paid service/maintenance charge | ৯৬,০০০ টাকা |
| Electricity bill-supported vacancy allowance | (১,০০,০০০ টাকা) |
| Gross rental value | ১১,৯৬,০০০ টাকা |
| ২৫% statutory deduction | (২,৯৯,০০০ টাকা) |
| Other admissible deduction ও special income-এর আগে balance | ৮,৯৭,০০০ টাকা |
৫. Security Deposit, Salami ও বিশেষ ভাড়া আয়
Finance Act 2026 special rental income-এর treatment গুরুত্বপূর্ণভাবে পরিবর্তন করেছে। Agreement বা receipt voucher-এ যে নামই থাকুক, lease receipt-এর প্রকৃত আইনগত character যাচাই করতে হবে।
Refundable বা adjustable deposit
২০,০০,০০০ টাকা deposit-এর মধ্যে year-end-এর আগে ৭,২০,০০০ টাকা adjust/return হলে outstanding ১২,৮০,০০০ টাকা; এর ১০% অর্থাৎ ১,২৮,০০০ টাকা special rental income। Balance-টি Assets & Liabilities Statement-এর সঙ্গে reconcile করুন।
Non-refundable salami বা premium
Non-refundable ও non-adjustable amount receipt year-এ সম্পূর্ণ special rental income। Statutory condition সাপেক্ষে taxpayer lease term বা পাঁচ বছর—যেটি কম—সে সময়ের মধ্যে spread করার option নিতে পারেন। পরবর্তী বছরে repayment হলে relevant year-এ deduction পাওয়া যায়।
Special rental income-এর অন্যান্য trigger
- ধারা ৩৮(১)(ঙ)-এর statutory deduction-এর unspent অংশ claim করা।
- Accounting adjustment ছাড়া Other Property-এর inadmissible deduction।
- Other Property expense-এ Part 7 অনুযায়ী প্রয়োজনীয় TDS না কাটা।
- Special rental income-এর বিপরীতে Third Schedule allowance নেই; regular rate প্রযোজ্য।
৬. ধারা ১০৯-এর Rent TDS, Banking ও Refund
ধারা ১০৯ অনুযায়ী কোনো statutory specified person listed property rent নিলে rent payment-এর সময় ১০% tax deduct করে। প্রত্যেক ordinary residential tenant-এর ওপর এই obligation নেই। Payer-কে নিজের legal status যাচাই করে বর্তমান withholding rule ও NBR process অনুসরণ করতে হবে।
১০% Rent TDS-এর উদাহরণ
| Office rent example | Amount |
|---|---|
| Gross monthly rent | ১,০০,০০০ টাকা |
| Section 109 TDS @ 10% | ১০,০০০ টাকা |
| Landlord-এর হাতে cash | ৯০,০০০ টাকা |
| Landlord-এর reportable gross rent | ১,০০,০০০ টাকা |
No-deduction certificate ও refund route
Prescribed application-এর ভিত্তিতে উপকর কমিশনার owner-এর taxable income নেই বা income exempt—এ মর্মে certificate দিলে certificate কার্যকর থাকা পর্যন্ত section 109 deduction বন্ধ থাকে। Tax determination-এর পর ধারা ১০৯ ও ১৬৩ অনুযায়ী full/excess deduction refund বা lawful adjustment হতে পারে; outstanding demand ও statutory process প্রযোজ্য।
Banking-channel discipline
NBR-এর ২০২৬–২৭ নির্দেশিকা অনুযায়ী এক বা একাধিক tenant-এর কাছ থেকে মোট monthly house rent ২৫,০০০ টাকার বেশি হলে owner-কে prescribed bank-account route-এ receipt maintain করতে হয়। ধারা ৭২(৩)-এর order/rule না মানলে ধারা ২৬৭-এর penalty framework প্রযোজ্য হতে পারে। Business ও Other Property deduction-এও আইন যেখানে bank transfer চায়, সেখানে cash payment ঝুঁকিপূর্ণ।
Landlord–tenant evidence trail
- Lease, rent schedule, tenant identity ও specified-person analysis।
- Gross rent invoice/receipt ও bank statement—শুধু net-after-TDS amount নয়।
- Government deposit/challan/electronic reference ও TDS certificate।
- e-Return source-tax credit entry এবং refund/adjustment application।
৭. e-Return Reporting, প্রয়োজনীয় নথি ও সাধারণ ভুল
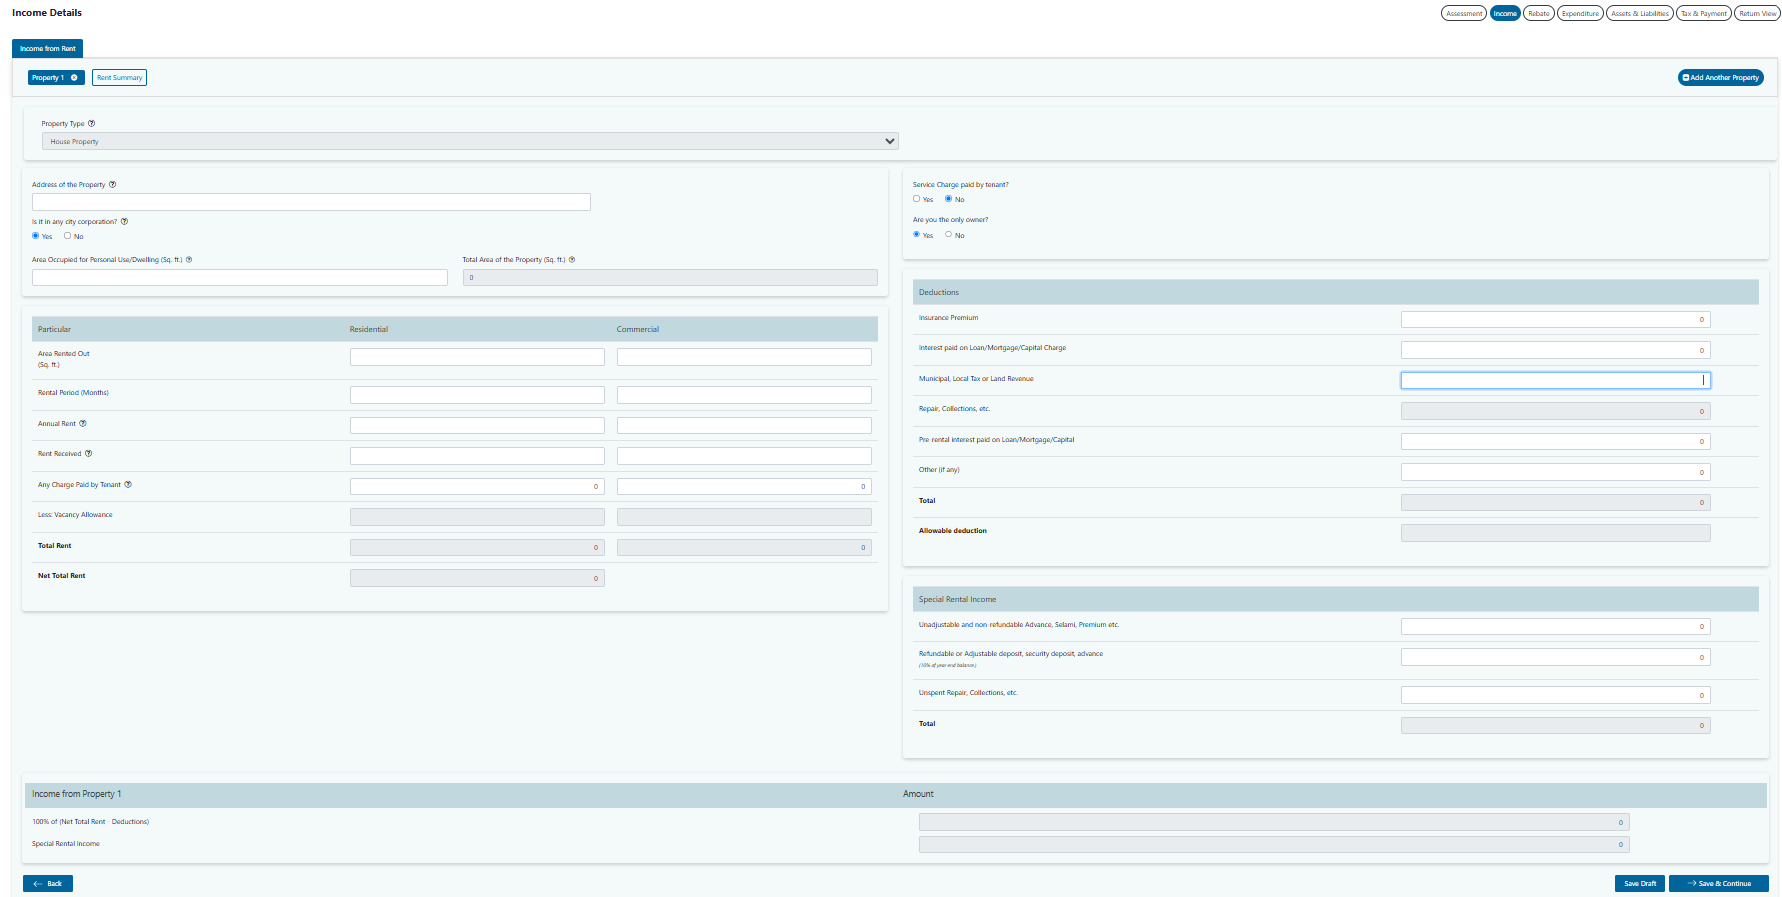
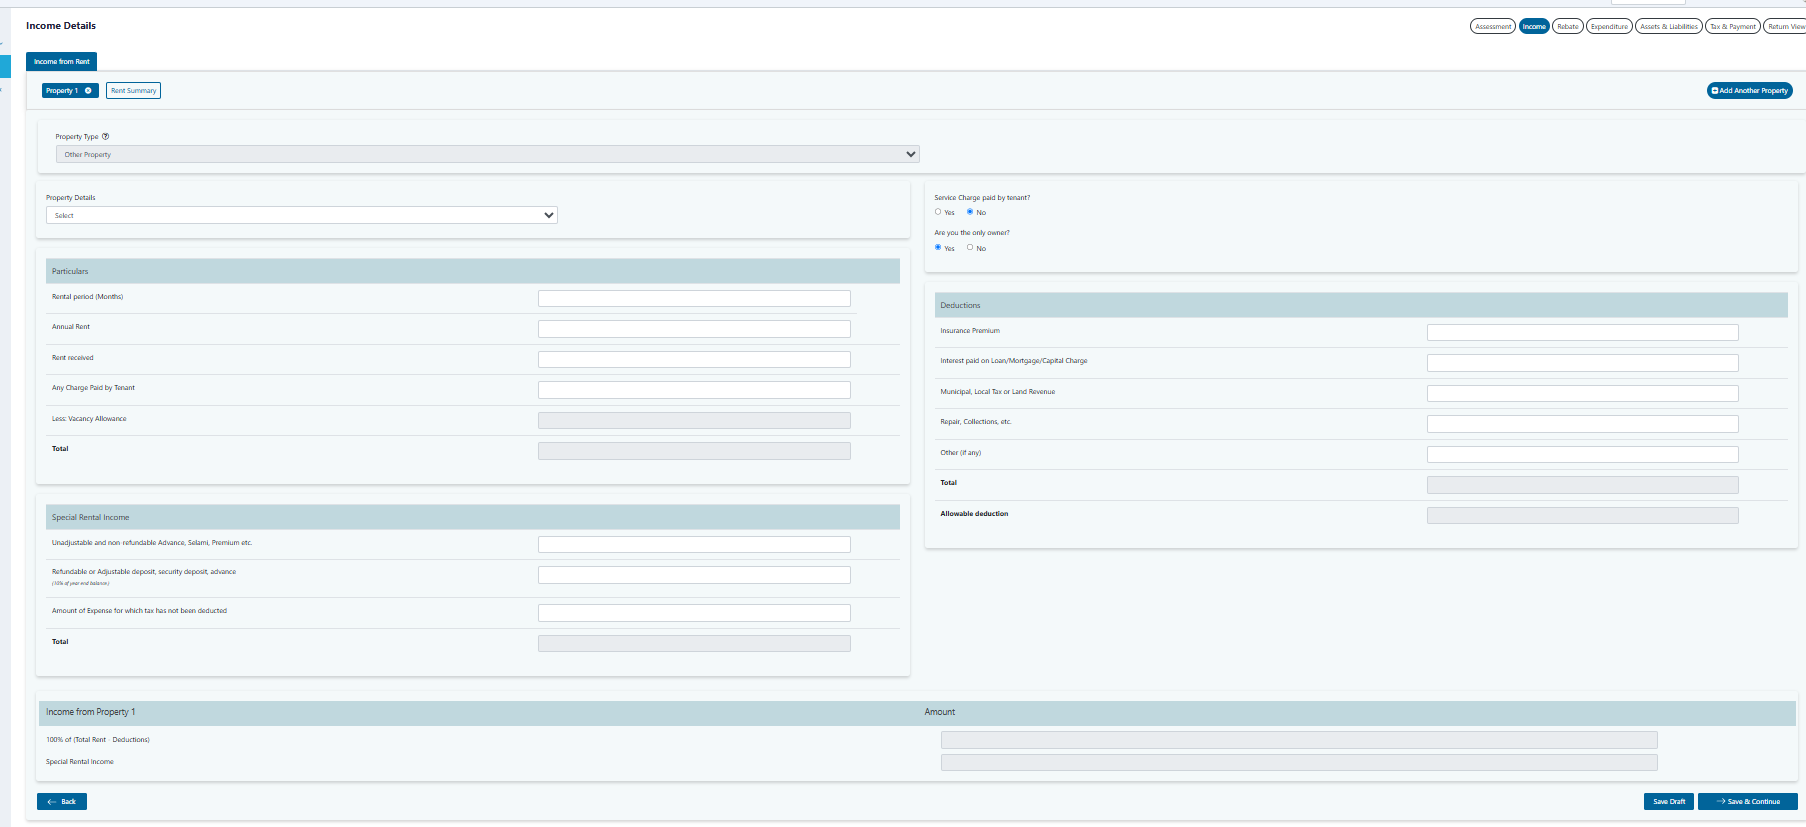
আইনগত classification-এর সঙ্গে matching e-Return Property Type ব্যবহার করুন। প্রতিটি property আলাদাভাবে add, rental period ও tenant-paid charge complete এবং Tax & Payment-এ source-tax credit নেওয়ার আগে Rent Summary review করুন।
House Property entry
- House Property select করে address, ownership, total area ও personal-use area দিন।
- Residential ও commercial rented area, period, annual rent ও rent received আলাদা করুন।
- Tenant-paid charge, vacancy ও শুধু admissible deduction দিন।
- Deposit, salami/premium ও other special rental income designated field-এ দিন।
Other Property entry
- সঠিক property detail, rental period, annual rent ও rent received দিন।
- Support থাকলে tenant-paid charge ও vacancy enter করুন।
- Other Property framework অনুযায়ী qualifying deduction দিন।
- যে expense-এ required TDS কাটা হয়নি, তার field review করুন।
যে documents রাখবেন
| Document | কেন প্রয়োজন |
|---|---|
| Title/ownership paper, lease ও rent schedule | Property, rent করার অধিকার ও contractual amount প্রমাণ |
| Bank statement ও rent receipt | Gross receipt, deposit ও banking compliance reconcile |
| Vacancy period-এর electricity bill | Statutory vacancy allowance support |
| Insurance, tax, fee ও loan-interest record | ধারা ৩৮ deduction support |
| Deposit/advance ledger ও repayment evidence | Year-end balance ও Assets & Liabilities consistency |
| TDS certificate ও government-deposit reference | Source-tax credit বা refund/adjustment support |
সাধারণ filing error
- Gross rent-এর বদলে TDS কাটার পর net cash report করা।
- Residential property-তে ৩০% বা Other Property-তে ২৫%/৩০% deduction ব্যবহার করা।
- Tenant-paid service/maintenance charge বাদ দেওয়া।
- Electricity bill ছাড়া vacancy claim করা।
- Year-end deposit-এর ১০% rule বাদ দেওয়া বা liability statement না মিলানো।
- Certificate ও government-deposit information না মিলিয়ে TDS credit নেওয়া।
৮. বাড়িওয়ালার রিটার্ন চেকলিস্ট
- সব rented asset list করে House Property ও Other Property classify করুন।
- Own-use, residential, commercial ও part-year portion আলাদা করুন।
- Annual value, gross rent, tenant-paid charge ও vacancy evidence reconcile করুন।
- Property category অনুযায়ী শুধু অনুমোদিত deduction দিন।
- Security deposit, adjustable advance, salami ও premium balance review করুন।
- প্রতিটি tenant section 109-এর specified person কি না যাচাই করুন।
- Credit claim-এর আগে TDS certificate ও government-deposit reference মিলান।
- Assets & Liabilities consistency complete করে final return file রাখুন।
৯. Roy Law Nexus যেভাবে সহায়তা করতে পারে
বাড়িওয়ালা, property investor, withholding obligation থাকা tenant এবং rented premises/equipment ব্যবহারকারী business-এর জন্য Roy Law Nexus সমন্বিত legal ও tax support প্রদান করে।
Property ও lease classification
Asset, ownership, use, bundled service ও lease term review করে House Property, Other Property বা অন্য lawful treatment নির্ধারণ।
Rental-income computation
Gross rental value, vacancy, ২৫%/৩০% deduction, loan interest ও property-specific admissible expense হিসাব।
Deposit ও premium review
২০২৬ rule অনুযায়ী refundable/adjustable deposit, advance, salami, premium ও Assets & Liabilities reconciliation।
Rent TDS compliance
Landlord ও tenant-কে section 109, withholding record, government deposit, certificate ও no-deduction application-এ সহায়তা।
e-Return ও refund support
Property entry, source-tax credit এবং lawful refund, adjustment বা carry-forward request প্রস্তুত/পর্যালোচনা।
Assessment ও dispute representation
Notice, audit, assessment, appeal, কর আপিল ট্রাইব্যুনাল এবং আইনগতভাবে প্রযোজ্য Income Tax Reference-এ সহায়তা।
১০. সাধারণ প্রশ্ন ও উত্তর
করযোগ্য rental income কি শুধু monthly rent × 12?
না। Statutory gross-rental formula, admissible deduction এবং special-rental-income rule প্রয়োগ করতে হবে।
Residential house-এ statutory deduction কত?
Listed collection, utility, service, repair ও maintenance expense group-এর জন্য gross rental value-এর ২৫%, Act-এর শর্ত সাপেক্ষে।
Commercial house-এ statutory deduction কত?
ঐ statutory expense group-এর জন্য gross rental value-এর ৩০%।
Rented machinery বা land-এ ২৫%/৩০% ব্যবহার করা যাবে?
না। Other Property-তে ধারা ৩৮(২), relevant ধারা ৪৯–৫৫ ও bank-transfer condition প্রযোজ্য।
Refundable security deposit কি সম্পূর্ণ tax-free?
বর্তমান ২০২৬ rule-এ নয়। Year-end outstanding refundable/adjustable balance-এর ১০% special rental income।
প্রত্যেক tenant কি ১০% rent TDS কাটবেন?
না। Section 109 statutory specified-person tenant ও listed property-এর ক্ষেত্রে প্রযোজ্য।
Company tenant-কে landlord কি TDS না কাটতে বলতে পারেন?
শুধু বক্তব্য যথেষ্ট নয়। Section 109(3) অনুযায়ী উপকর কমিশনারের valid prescribed certificate প্রয়োজন।
Rent TDS final tax-এর চেয়ে বেশি হলে কী হবে?
ধারা ১০৯, ১৬৩ ও refund provisions অনুযায়ী assessment, outstanding dues ও procedure সাপেক্ষে excess amount refundable/adjustable হতে পারে।
একাধিক rented property কীভাবে report করব?
প্রতিটি asset-এর জন্য separate e-Return property record তৈরি করে consolidated Rent Summary review করুন।
১১. প্রধান আইনগত উৎস
আয়কর আইন, ২০২৩—ধারা ৩৫–৩৯
২০২৬ amendment-সহ rental-income definition, computation, deduction ও special rental income।
আয়কর আইন, ২০২৩—ধারা ১০৯
Specified-person tenant-এর ১০% rent TDS, full/excess refund ও no-deduction certificate।
আয়কর আইন, ২০২৩—TDS certificate ও credit বিধান
Certificate, deposit ও source-tax credit framework।
আয়কর আইন, ২০২৩—ধারা ১৬৩
Excess tax-এর refund, prior-demand adjustment ও carry-forward option।
আয়কর আইন, ২০২৩—ধারা ২২৪–২২৬
Refund-এর অধিকার ও statutory adjustment/payment process।
আয়কর আইন, ২০২৩—ধারা ২৬৭
ধারা ৭২(৩)-এর order বা rule না মানার penalty framework।
NBR আয়কর নির্দেশিকা ২০২৬–২৭
Official rental-income example, banking guidance ও e-Return instruction।
অর্থ আইন, ২০২৬
Current-year amendment-এর NBR প্রকাশিত সরকারি কপি।
NBR Income Tax Rules
বর্তমান official withholding ও procedural rule।
NBR e-Return FAQ
Official online-filing ও source-tax-credit guidance।
১২. উপসংহার
নির্ভরযোগ্য rental-income return property classification ও complete evidence trail দিয়ে শুরু হয়। Gross rental value হিসাব, property অনুযায়ী সঠিক deduction, special rental income শনাক্ত, section 109 tax আলাদা reconcile এবং প্রতিটি property সঠিক e-Return category-তে report করতে হবে। Mixed-use, deposit বা withholding arrangement জটিল হলে filing-এর আগে review নিন।
লেখক পরিচিতি
স্বদীপ রায় সজীব
এডভোকেট, বাংলাদেশ সুপ্রীম কোর্ট
সদস্য, ঢাকা বার অ্যাসোসিয়েশন ও ঢাকা ট্যাক্স বার অ্যাসোসিয়েশন
আইনি ঘোষণা: এই নিবন্ধটি ৬ অক্টোবর ২০২৬ পর্যন্ত পর্যালোচিত প্রাথমিক সরকারি উৎসের ভিত্তিতে সাধারণ আইনগত ও কর-তথ্য প্রদান করে। Ownership, use, lease term, residency, accounting method, tenant status, record ও পরবর্তী সরকারি পরিবর্তন অনুযায়ী treatment ভিন্ন হতে পারে। এটি নির্দিষ্ট মামলার পরামর্শ নয় এবং আইনজীবী-মক্কেল সম্পর্ক সৃষ্টি করে না।